Retirement Is a Number, Not an Age: The FIRE Rule
Discover the 25x rule and the 4% rule behind the FIRE movement, plus the 4 distinct paths — LeanFIRE, FatFIRE, BaristaFIRE, and CoastFIRE — to calculate your own financial independence number and finally retire on your own terms.
Yannick
5/8/20243 min read
The Paradigm Shift: Retirement Is a Number, Not an Age
In this episode, we're going to dig into the very foundations of the FIRE movement (Financial Independence, Retire Early).
By the end of this article, you'll understand the most important paradigm shift in personal finance, and you'll know exactly how to calculate your own "freedom number."
For generations, society has conditioned us to see retirement as a chronological milestone (which is so true in my home country, France). You work for 40 to 45 years, and once you reach 64 (or whatever age triggers your state pension), you can finally stop.
The FIRE movement completely flips this script.
Retirement isn't an age. It's a number.
You don't need to be 64 to retire. You simply need to build up a large enough pool of invested assets so that growth and dividends can cover your living expenses for the rest of your life. Once your investments generate enough passive income to pay your bills, work becomes entirely optional. You are financially independent.
But how do you know what amount is "enough"? That brings us to the core math behind FIRE.
The Core Math: The 25x Rule (and the 4% Rule)
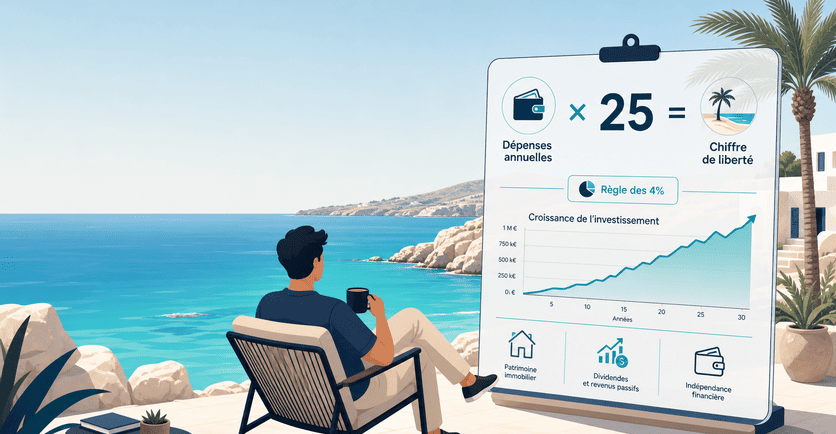
If there's only one concept you take away from this episode, let it be this: the 25x rule (personally, I prefer using 30x for a bigger safety margin).
To find the exact amount you need to reach financial independence, you should base your calculation on your annual expenses — not your current salary.
The 25x rule states that you're financially independent once you've saved and invested 25 times your annual expenses.
€ {Your FIRE Number} = € {Your Annual Expenses} × 25
Why 25? This calculation is based on a well-known financial concept called the 4% rule (derived from a landmark study known as the Trinity Study). This study showed that if you invest your money in a diversified portfolio of stocks and bonds, you can safely withdraw 4% of your initial capital in the first year, then adjust that amount for inflation each following year, with a very high probability that your money will last 30 years or more.
Mathematically, withdrawing 4% of a portfolio is exactly equivalent to multiplying your annual expenses by 25.
Let's look at a few examples:
The Minimalist: If you live comfortably on €40,000 a year: €40,000 × 25 = €1,000,000 Your FIRE number is €1 million.
The Average Spender: If you live comfortably on €60,000 a year: €60,000 × 25 = €1,500,000 Your FIRE number is €1.5 million.
The Big Spender: If you live comfortably on €100,000 a year: €100,000 × 25 = €2,500,000 Your FIRE number is €2.5 million.
Once you've reached and invested your specific number, you can stop working — forever.
The 4 Flavors of FIRE: Which Path Is Yours?
Because everyone's financial goals and lifestyle preferences differ, the FIRE community has split into four distinct paths. As you start this journey, it helps to know which approach appeals to you most:
1. LeanFIRE
The mindset: Minimalist and efficient.
The goal: Retire on a tight budget (generally annual expenses under €40,000).
The advantage: Since your target number is lower, you can reach financial freedom much faster.
2. FatFIRE
The mindset: Abundant and luxurious.
The goal: Retire with a high standard of living (generally annual expenses above €100,000).
The advantage: You don't have to compromise on travel, dining out, or living in an expensive city — though it takes longer to build up the required capital.
3. BaristaFIRE
The mindset: Semi-retired.
The goal: You save a significant amount of money, leave your stressful 9-to-5 office job, and switch to an enjoyable, low-stress job (part-time or full-time) to cover your basic expenses or health insurance, while letting your capital keep growing in the background.
4. CoastFIRE
The mindset: Maximum security, front-loaded.
The goal: You save aggressively during your 20s or 30s until your retirement accounts reach a point where, even if you never add another cent, compound interest will grow them into a comfortable retirement fund by traditional retirement age. From there, you can "coast" by taking any job that simply covers your current monthly bills.
Your Homework
Before moving on to the practical steps of budget optimization and investing, you need to know your starting coordinates.
Take 10 minutes today to estimate your annual expenses.
Don't worry about being precise down to the cent just yet. Just jot down a rough estimate of what it costs you to live for one year (rent/mortgage, food, insurance, transportation, leisure).
Multiply that number by 25 (or more, like 30).
Write that number down on a sticky note or in a digital notepad. That's your final destination.
Questions about the 25x rule? Drop them in the comments!